
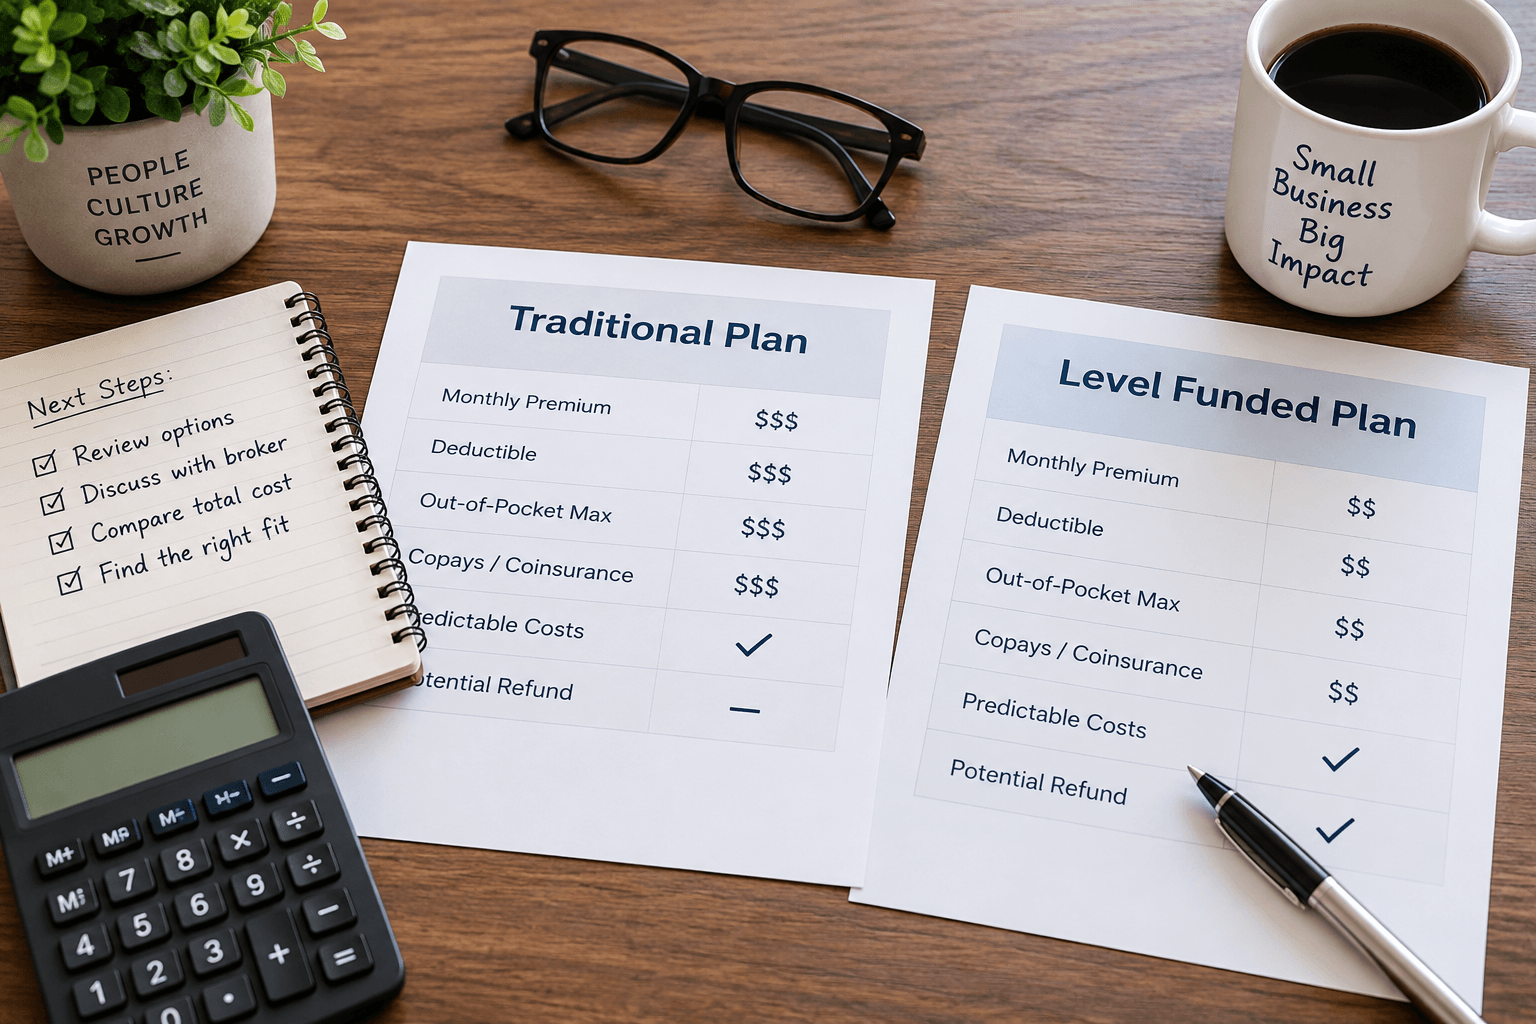
I’m always a little surprised when I talk to a small employer and level funding has never even come up.
For companies with fewer than 50 employees, it can be another way to approach group health insurance, especially when you’ve got a relatively healthy group.
Here’s the basic idea.
The insurance company looks at the group and estimates what claims are likely to look like for the year. Your monthly cost is set from there, so you’re not dealing with the ups and downs you’d see in a traditional self-funded plan.
If the group performs well, you could save a pretty significant amount on premiums. Also, depending on how the plan is set up and how claims come in, there can be money returned to the employer.
Now, I’m not saying level funding is right for everybody.
What gets me is when a business owner has been renewing the same kind of plan year after year and nobody’s ever said, “Hey, there’s another option we should at least look at.”
That’s the conversation I’d want to have.
If you’ve got fewer than 50 employees, ask your broker:
Have we looked at level funding, and does it make sense for our group?
Maybe the answer is no. That’s fine.
But I’d rather know we looked at it than find out later it was sitting there the whole time.
#HealthInsurance #EmployeeBenefits #SmallBusiness #BusinessOwners #GroupHealthInsurance #WebbInsuranceGroup

